The strongest contributors to performance during the month were MediaTek, Instalco, Taiwan Semiconductor and Allegro.
MediaTek was our largest contributor. August sales, reported in September, increased 44% year on year to NT$64.2 billion and 32% from July. The company also launched its new Dimensity 9600 Pro smartphone chip during the month, using 2nm technology.
Instalco announced further contract wins, including a SEK54 million electrical installation project at Kungälv Arena and a NOK40 million ventilation and design assignment in Stavanger.
Taiwan Semiconductor reported another strong month of sales. August revenue increased 53% year on year to NT$514.8 billion and 10% from July, taking growth for the first eight months to 39%.
Allegro raised its full-year guidance following stronger trading. Group merchandise sales grew 14.4% in the second quarter, with growth approaching 15% for the year to date during early Q3. Management now expects full-year merchandise sales growth of 13–15% and adjusted EBITDA growth of 13–17%. International marketplace sales doubled in the first ten weeks of Q3, while the Polish business also continued to accelerate.
The weakest contributors were flatexDEGIRO, Yonex, BuySell Technologies and Nittetsu Mining.
flatexDEGIRO was our largest detractor during a month of significant leadership changes. Chairman Hans-Hermann Lotter resigned as chairman on 10 September, with Stefan Müller taking over on an interim basis.
Yonex weakened despite having raised its full-year earnings forecast in August. Its latest quarterly sales increased 14%, while operating profit rose 9%. Higher raw-material costs and spending on marketing and staff limited profit growth. The latest outlook calls for full-year operating profit of ¥18.9 billion, up 14%.
BuySell Technologies also declined despite a positive operating update. Its August figures, released on 17 September, showed home visits increasing 32% year on year to 42,011, while the value of goods purchased through home visits rose 61% to ¥1.84 billion. Management is aiming to exceed its annual plan of 530,000 visits. The company also agreed to acquire HKS Victory Japan, which operates the Tokyo Ichiba purchasing-store chain, with completion scheduled for 30 October.
Nittetsu Mining announced a setback at its Arqueros copper project in Chile. Heavy rainfall damaged access roads and bridges, while electricity approvals also took longer than expected. However we see this as a temporary setback and for Nittetsu to begin copper production soon, with major balance sheet sales leading to a significant increase in buybacks.
Key market events and trends
Year-to-date, the MSCI World index is up 17% in EUR. Returns have been driven by particularly robust profit growth, for which consensus estimates now point to more than 25% for 2026, while profit growth estimates for 2027 have been raised to 17% (from 14%). Excluding the rising interest rates, particularly in the US, share prices would have risen by more than 20% so far.
Bond yields around the world are up, and real interest rates in the US touched levels not seen since the early 2000s. Part of this rise can be explained by energy-driven inflation, but credit demand has also increased as governments continue to run unsustainable deficits, while capex investments in AI data centers push credit demand up further. As credit demand has now surpassed what the system can meet, real interest rates rise. Simply put, there is more demand for capital than supply, propelling the cost of capital upwards.
With share prices up 17% during 2026 and profits likely to surpass 25%, there is an implicit valuation contraction justified by the higher interest rates. Firstly, investors will be tempted to sell shares to generate a predictable income stream from bonds in the coming ten, 20, or 30 years. Secondly, the present value of shares will decrease as the discount rate rises.
Currently, the earnings growth rate appears able to offset the impact of higher interest rates. But as interest rates increase further, such as to 6.0% for the US 10-year yield, the equity markets will encounter problems. On the other hand, shares should perform well if inflation weakens during 2027, as is widely expected, with less headwind from the higher interest rates.
Q3 2026 reporting season is around the corner, and profits for S&P 500 companies are expected to be up 30%, spurred by remarkable growth of 65% by the tech sector. In Europe, the Stoxx 600 is heading for profit growth of 17%, thanks to the energy sector.
Portfolio changes during the month
We added no new holdings during September.
Fund positioning
We remain optimistic about the opportunities across the portfolio. Our main investment themes continue to be Japanese corporate reform, Asian technology, financial market infrastructure and European businesses improving their operations and capital allocation. Our focus remains on earnings growth, cash generation and how management teams use the capital available to them.
*MSCI ACWI ex USA NTR USD Index in EUR
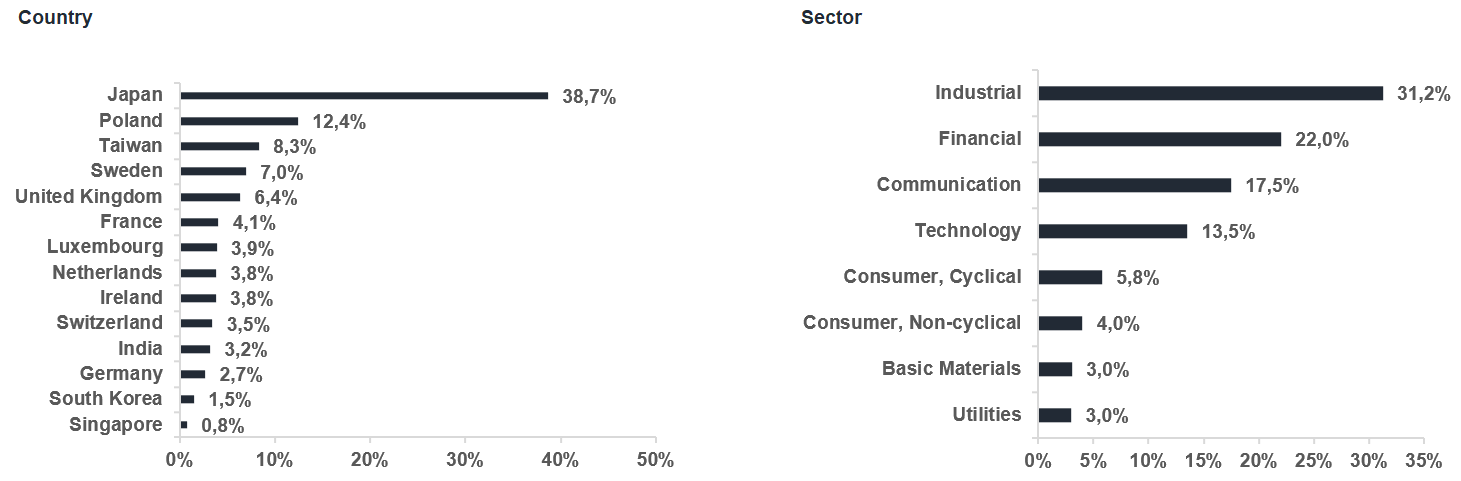
* The performance-based fee is 10% of the part of the total return that exceeds a so-called return threshold defined as the MSCI ACWI ex USA Net Total Return USD Index In EUR, and is calculated according to the "high watermark" principle.

WARSAW STOCK EXCHANGE
TSMC
Bank Pekao
Instalco
Mediatek
Riskinformation
Past performance is not a guarantee of future returns. The value of shares in the fund may go up or down, and an investor may not get back the amount originally invested
Monthly Newsletter | 9 okt 2026
Monthly Newsletter | 8 okt 2026
Monthly Newsletter | 7 okt 2026