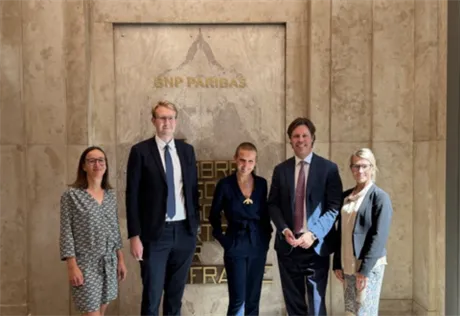
A couple of weeks ago we visited Paris to meet with French bank BNP Paribas. BNP Paribas is a relatively new holding in BMC Global Select.
A brief summary of the bank:
- BNP Paribas is one of Europe's largest banks, with 178,000 employees and a balance sheet of EUR 3 trillion. The biggest bank in the Nordic region is Nordea, with a balance sheet of EUR 0.7 trillion, proving that BNP is a key market player.
- BNP Paribas generates around 10% of its profit in France. Other important countries for the bank are Belgium, Italy, Spain, and the US. It also has smaller operations in Poland.
- Jean-Laurent Bonnafe has held the CEO position since 2011, making him one of the CEOs to have held this post the longest. He seems likely to step down in 2028, but until then he continues to push the bank onward, with a rising share price as a result.
- As is often the case with banks of this size, there are few outstanding legal issues. In BNP's case, there is a dispute associated with earlier loans to Sudan. We anticipate this being resolved within the next six to 12 months, and we see no reason for it to impact the positive investment case.
We believe the bank has several good years ahead of it, something that our meeting confirmed. We see this primarily being driven by:
1. Higher interest rates in Europe will lead to many years of increasing revenues as the loans on the loan book are repriced at a better yield curve. There is also robust demand for investment banking services in Europe, as the continent has now roused itself and decided to focus on infrastructure, energy, and defense.
2. Solid demand for more financial products in Europe, plus asset management with capital now shifting from regular bank accounts and into the equity markets. Europe must "harness its abundant savings" as the bank puts it. We consider BNP's acquisition of AXA to be a key step in scaling within asset management, with the acquisition placing BNP among the top three asset managers in Europe.
3. The bank has completed its large acquisitions. We may see some smaller divestments, but otherwise "sweating the assets" is now in focus to reduce the cost/income ratio. AI investments have already succeeded in halving the time for a mortgage application in its French operations.
4. Higher revenues and lower costs suggest profits will likely increase significantly. During Q2, turnover picked up by 12% (the AXA acquisition accounted for around 3% of this) and profits increased by 33%. We expect this trend to continue. We made it clear that we would like to see more share buybacks as the bank generates vast amounts of capital, and we believe it will increase the pace of its buybacks from 2027 onward.
5. Valuation appears attractive at a dividend yield of more than 6% (the bank distributes 50% of profits) and a P/E (24M forward) of 7.1x, which is considerably lower than many other European banks. We are quite certain that equity analyst estimates are too low, as this is clearly a bank with ambitions, as it says itself, and that it will likely continue to surpass market expectations.
All in all, BNP Paribas is an exciting "special situation" with several interesting upcoming triggers.